
Will home prices drop in 2026? The short answer: nationally, no broad crash is expected, and the forecasts call for flat to low-single-digit growth instead. The National Association of Realtors' September 2026 existing-home sales report, released October 13, put the median U.S. existing-home price at $417,500, up just 1.3% from a year earlier, while J.P. Morgan Research projects zero national price growth for 2026, the slowest pace in about 15 years.
As a luxury real estate specialist with 19 years of experience in Apalachee Farms and Northeast Metro Atlanta, I get this question every week, and it deserves a straight answer, not a headline. Here is what the September data actually shows, why the major forecasters agree that flat is the most likely outcome, and what that means for buyers and sellers in Dacula, Gwinnett County, and the surrounding communities.
What the Latest Home Price Data Says
The freshest national snapshot came two days ago. NAR's September 2026 existing-home sales report showed sales up 1.5% from August to a 3.99 million seasonally adjusted annual rate, though still down 2.2% year over year. Housing inventory rose to 1.60 million units, a 4.8-month supply, and the median existing-home price ticked up 1.3% year over year to $417,500. That is the definition of a flat market: sales steadying, supply rebuilding, and prices moving sideways rather than soaring or tumbling.
The price slowdown has been building all year. After the rapid appreciation of 2021 through 2023, gains have cooled to a crawl in 2026. Several forecasters describe it as a correction in pace, not a correction in price. J.P. Morgan expects flat 0% national growth for 2026 before a modest +3% in 2027, while Zillow's 12-month outlook is +0.0%, Morgan Stanley sees +2%, and the Fannie Mae expert panel consensus is +2.5%. Realtor.com trimmed its forecast to about 1.2%. Only NAR's Lawrence Yun is meaningfully more optimistic, at roughly 4%, and he is the clear outlier.
One number worth understanding: when prices rise at 1% to 2% and inflation runs near 4%, the real, inflation-adjusted price of a home is actually falling. That is why buyers tell me homes finally feel more affordable relative to incomes, even though the sticker prices look similar to last year. For the first time in more than a decade, income growth is outpacing home price growth. Read my breakdown of the Great Housing Reset here for the longer view on this shift.
price, year over year
NAR's September 2026 report: median price of $417,500, sales up 1.5% month over month to a 3.99 million annual rate, and inventory at a 4.8-month supply. Prices are moving sideways, not falling off a cliff.
Why Forecasters See Flat Prices, Not a Crash
The reason the forecasters cluster in the flat-to-modest range is that the conditions that cause crashes simply are not present. Here is how the major 2026 forecasts stack up, followed by the four structural reasons prices are expected to hold.
There Is Still a Housing Shortage
Estimates of the U.S. housing deficit range from about 1.2 million to 4.7 million homes. Builders have been adding units, but supply has not caught up to the households formed over the last decade. A shortage is the single strongest reason prices do not collapse: when there are more buyers than homes in most price ranges, sellers hold the floor.
Homeowners Have Record Equity, Not Negative Equity
The average homeowner holds record levels of equity today, a direct contrast to 2008, when millions owed more than their homes were worth. Because so many owners have built-up equity, there is no wave of distressed, forced sales pushing prices down. Foreclosure levels remain low, and the sellers who do list are choosing to sell, not being forced to.
Lending Standards Are Much Stricter Than 2008
The easy credit that fueled the last crash is gone. Today's buyers face documented income, full underwriting, and meaningful down payments. That keeps demand honest, which in turn keeps the market from inflating a bubble that would have to pop.
The Lock-In Effect Still Holds Inventory Back
Millions of homeowners are sitting on mortgages near 3% and 4%, and selling would mean trading them for a rate near 7%. Analysts estimate the lock-in effect has suppressed roughly 1.7 million sales and pushed prices about 7% higher than they would otherwise be. Until rates fall meaningfully, that is a slow leak of inventory, not a flood.
Will Prices Drop in Atlanta and Gwinnett County?
The national picture is flat, and the local picture is flat to slightly soft, which is actually the healthiest version of this market. Gwinnett County's median sale price was about $419,000 in June 2026, down roughly 4.7% year over year, and the county's typical home value sat near $408,800 in late July, down about 2.6% year over year, with homes going pending in about 34 days, according to Redfin and Zillow data. Metro Atlanta's median home price came in near $427,000 over the three months ending August 2026, roughly flat year over year.
In other words, the price declines that have happened are real but modest, concentrated in segments where inventory grew fastest, like entry-level and move-up homes. Luxury and amenity-rich properties, and golf course communities in particular, have held their value much better because their supply is structurally limited. That is the pattern I watch closely in Apalachee Farms: the premium sections resist the softness the wider county is seeing.
What Flat Prices Mean for Apalachee Farms, Section by Section
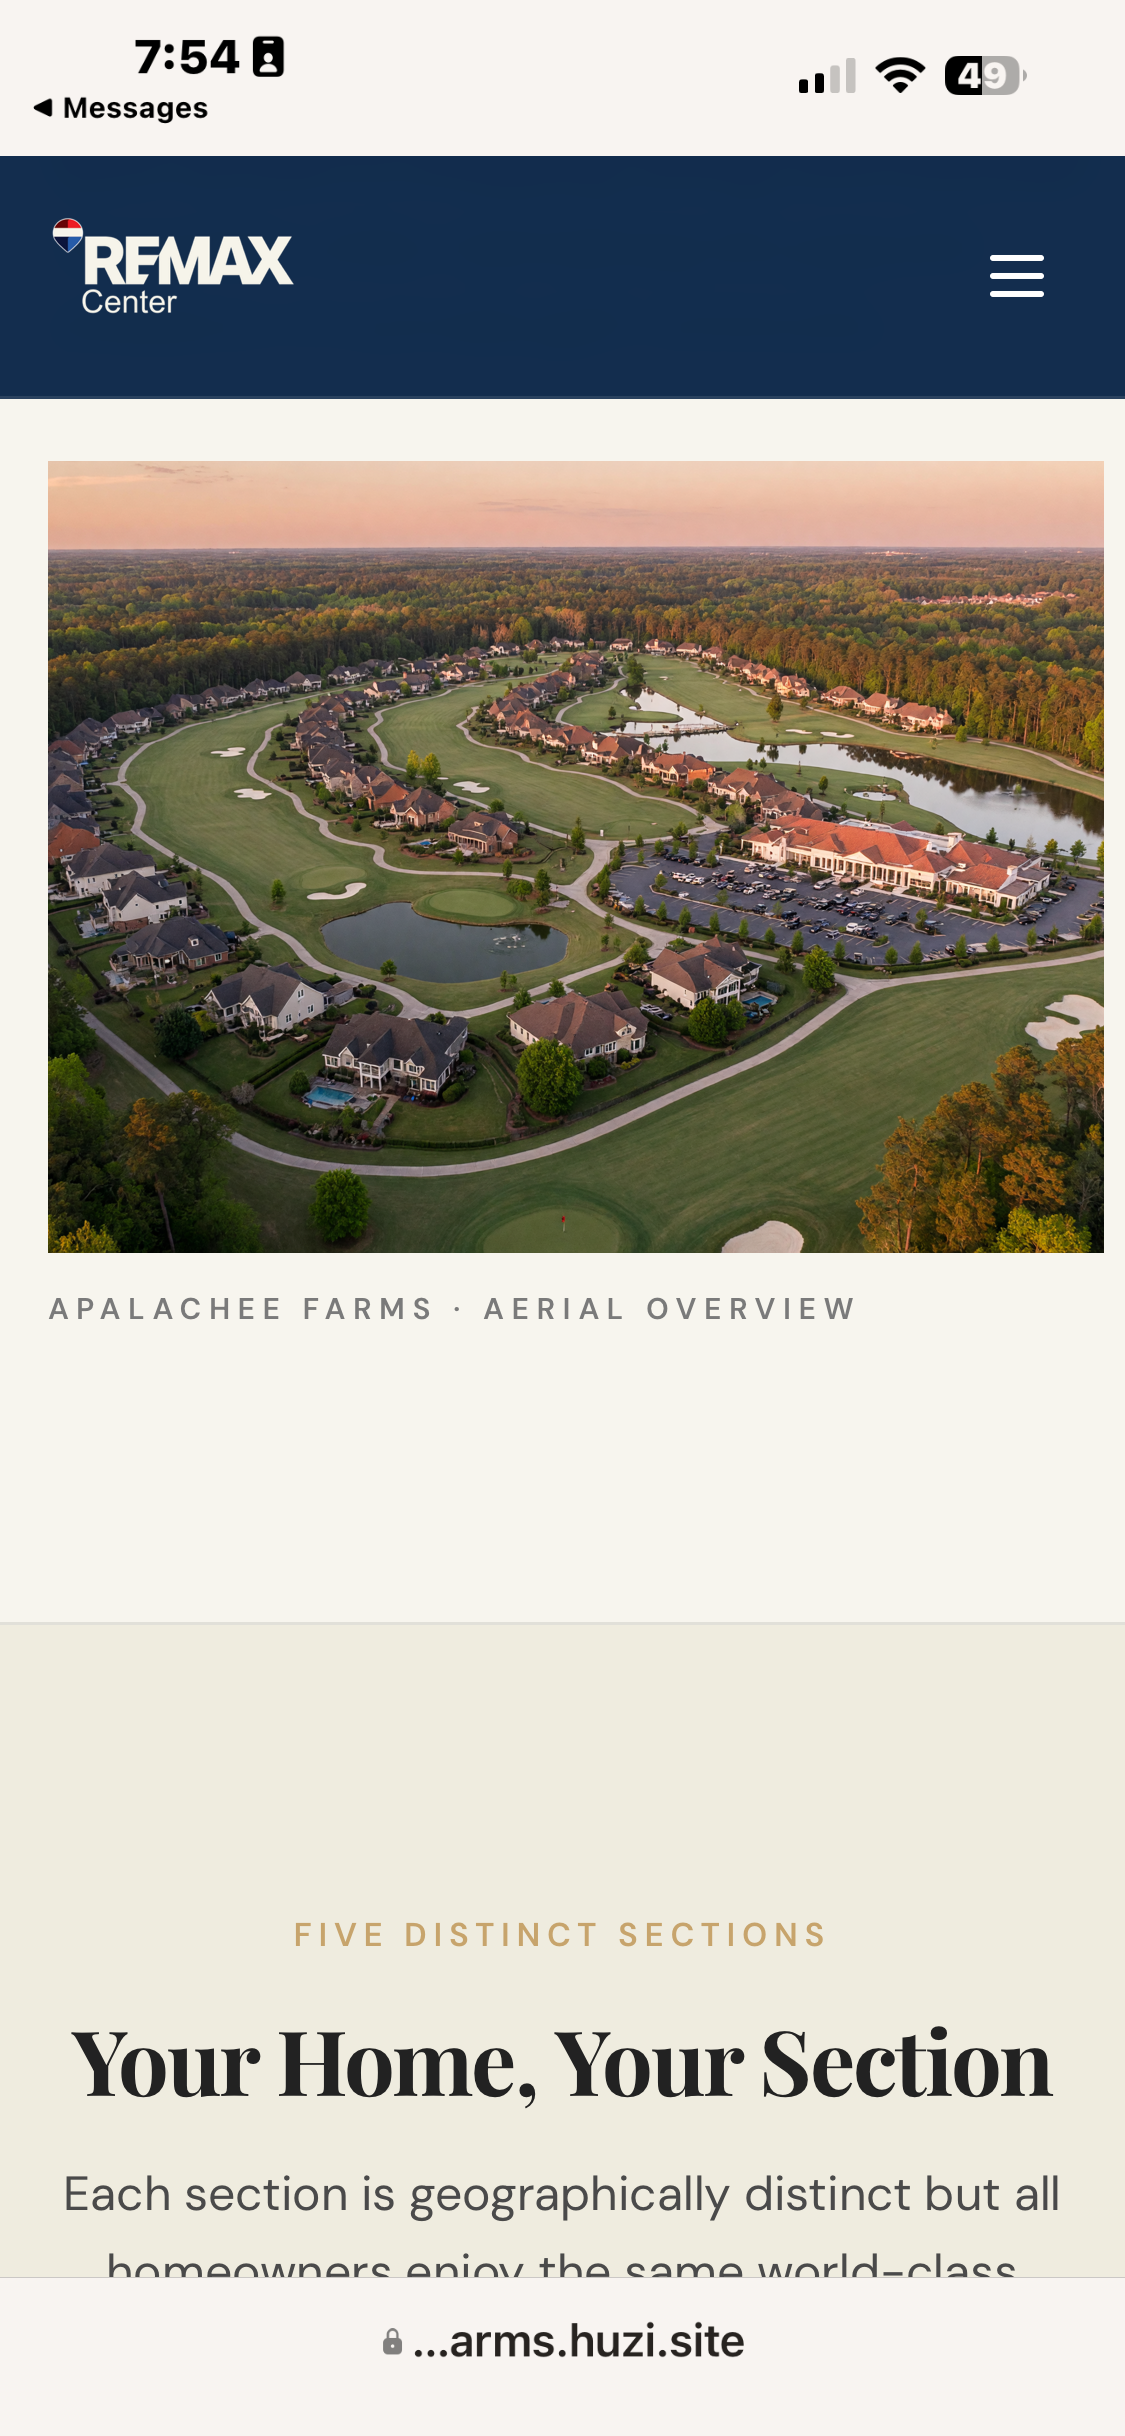
Apalachee Farms is a multi-dimensional community, roughly 587 homes across five geographically distinct sections, with prices running from about $500,000 to $1.3 million. A flat market does not hit every section the same way, and that is where local knowledge matters.
The Terraces, the entry-level section, shows the most negotiation room. These homes compete directly with new construction and resales across Dacula and Buford, and in a flat market that is where price cuts and concessions concentrate. Riverside, with its variety of floor plans, sits in the middle: consistent demand, but buyers there expect updated finishes and fair pricing. Sterling Green, the established section with consistent resale, behaves like a steady eddy; its homes turn over predictably, and pricing holds best when homes are updated.
Clubview and The Oaks at Apalachee Farms are the premium, golf-oriented sections, and they are the reason the community outperforms the wider county in a slowdown. Homes with Trophy Club of Apalachee views, larger lots, and upscale finishes are scarce, and scarcity is the strongest price support there is. In a flat national market, the buyers who can still afford the monthly payment at today's rates are competing for a very small pool of golf-front inventory, which is why these sections continue to hold their value best.
How to Win in a Flat-Price Market
For Buyers: Negotiate Terms, Not Just Price
In a flat market, the leverage is on your side, and it is worth more than a lower sticker price. Get pre-approved, compare written Loan Estimates from multiple lenders, and ask for a seller concession toward closing costs or a temporary rate buydown. With the 30-year fixed near 7%, a buydown can cut hundreds of dollars off your first-year payment, and sellers in this market are routinely agreeing to help because they know realistic terms close deals. Homes sitting on the market longer are your best negotiating opportunities, but move quickly on the right golf-front home, because in a scarce community those still attract competition.
For Sellers: Price From Today's Closed Sales
The biggest risk for a seller in a flat market is anchoring on an old number. Price from what comparable homes in your section actually closed for in the last 60 to 90 days, not from what a neighbor hoped to get in 2022. The first two to three weeks on market set your trajectory, so launch with the right price, make the home move-in ready, and decide your concession budget before you list. A strategic buydown or closing cost credit often protects your sale price better than a larger reduction later, and strong marketing, drone footage of the fairways, cinematic photography, earns the showing in the first place.
The One Line to Remember
A flat market is not a falling market, and it is not the 2008 crash redux. It is the most normal housing market we have had in years: prices steady, inventory rebuilding, and the balance of power finally tipping toward buyers. For sellers, that means realistic pricing and strong presentation. For buyers, it means negotiation room that has not existed since before the pandemic. The people who do best in this market are the ones who act on the data instead of waiting for a correction that forecasters do not expect.
Frequently Asked Questions About Home Prices in 2026
Are home prices actually falling right now?
Nationally, prices are roughly flat to up very slightly. The National Association of Realtors' September 2026 report, released October 13, put the median existing-home price at $417,500, up 1.3% from a year earlier. In Gwinnett County, the local numbers are cooler: the median sale price in June 2026 was down about 4.7% year over year, and the county's typical home value has slipped about 2.6% year over year. So we are seeing softness and small declines in price-sensitive segments, but not a broad crash, anywhere.
Will home prices crash in 2026 or 2027?
Every major forecaster says no. J.P. Morgan projects flat 0% national price growth for 2026, Zillow's outlook is +0.0%, Morgan Stanley sees +2%, and the Fannie Mae expert panel consensus is +2.5%. The reasons a crash is unlikely are structural: a housing shortage, record homeowner equity, stricter lending standards, and the lock-in effect that keeps inventory tight. A flat-to-modest market is the consensus, not a downturn.
Why do homes still feel expensive if prices are flat?
Because mortgage rates near 7% make the monthly payment far higher than the price alone suggests. Even a flat price can feel expensive when the payment on the same house has climbed by hundreds of dollars a month over two years. And in real terms, prices are already falling: a nominal gain of under 2% trails an inflation rate near 4%, which means the purchasing power of your dollar is growing faster than home prices for the first time in years.
What does flat price growth mean for buyers in Apalachee Farms?
It means you can negotiate without the panic of a rising market. Sellers in a flat market are more willing to accept a reasonable offer, contribute closing costs, or help buy down the rate, because they know a slower market rewards realistic terms. In Apalachee Farms, entry-focused sections like The Terraces and Riverside see the most negotiation room, while golf-front homes in Clubview and The Oaks hold their value because the supply of homes with Trophy Club views is genuinely limited.
What does it mean for sellers in Apalachee Farms?
Price your home from today's closed sales, not from what a neighbor hoped to get in 2022 or 2023. In a flat market, the first two to three weeks set the trajectory: a realistic list price generates showings and offers, while an optimistic one generates a price cut six weeks later. Condition, presentation, and marketing matter more than ever, and a strategic concession can protect your sale price by closing the gap between what buyers can pay and what you want to net.
Should I wait for prices to drop before buying?
Waiting has a real cost. If prices are flat, waiting for a crash means waiting for something the forecasters do not expect. Meanwhile, rates near 7% are the bigger variable, and if rates ease, demand typically surges and prices firm back up. The buyers who do best in a flat market are the ones who negotiate price and terms today, get a seller concession or buydown, and refinance if rates drop later. That is a plan built on data, not on hoping for a correction.
Wondering What a Flat Market Means for Your Home?
Lisa Harris combines nearly 20 years of Apalachee Farms market knowledge with section-level data from GAMLS and FMLS to help you price, negotiate, and plan with confidence. Whether you are buying or selling, she can show you exactly what the flat 2026 market means for your situation.

Lisa Harris, MBA, CLHMS GUILD
Lisa Harris is a CLHMS GUILD Certified Luxury Home Marketing Specialist serving Apalachee Farms, Dacula, and Northeast Metro Atlanta's premier golf course and country club communities. She has sold in Apalachee Farms for nearly 20 years and lived in the neighborhood for 10. With an engineering degree and an MBA, she combines data-driven pricing, cinematic marketing, and skilled negotiation to help buyers and sellers navigate markets like 2026. Her insights have been featured by RISMedia, Realtor.com, Inc. magazine, and Atlanta News First.
Information believed to be accurate but not guaranteed. National price and sales data sourced from the National Association of Realtors' September 2026 Existing-Home Sales report (released October 13, 2026), J.P. Morgan Research, Zillow, Morgan Stanley, Fannie Mae's Home Price Expectations Survey, Realtor.com, and NAR. Atlanta and Gwinnett data sourced from Redfin and Zillow market data. Apalachee Farms findings grouped regardless of MLS spelling variations. Contact Lisa Harris for the most current market information for your specific home.